Punts, Pixels, and Payouts: Surging Trends in Britain's Betting Landscape
Written by Nils Meier · Mar 30, 2026
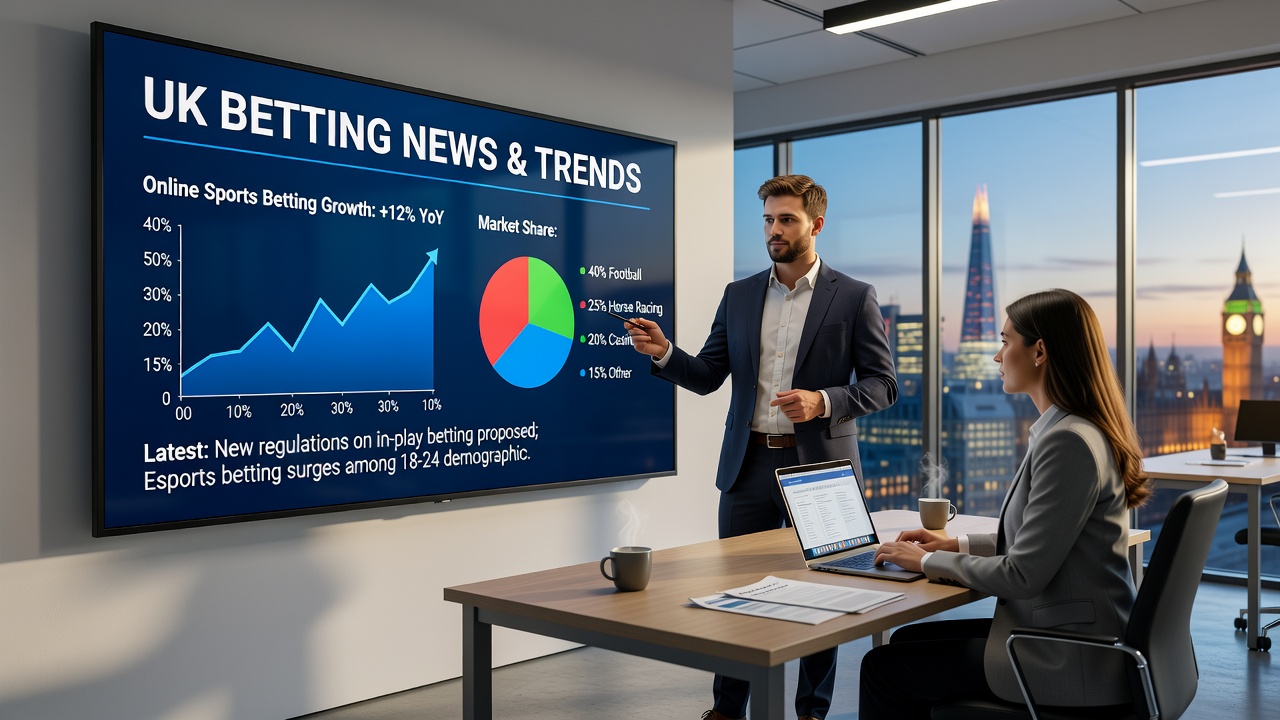
UK Gambling Operators Face 30% Licence Fee Surge: Government Unveils Consultation to Boost Enforcement
The Launch of a Pivotal Public Consultation
The UK government, acting through the Department for Culture, Media and Sport, has kicked off a public consultation that proposes sharp increases to Gambling Commission operating licence fees for gambling operators, particularly remote betting firms; this move seeks to better match cost recovery with the regulatory effort involved, operators' market share, and the risks they pose, all while the industry grapples with rapid growth and looming tax pressures. Launched recently, the consultation outlines options that could reshape how fees are structured, with the preferred path—Option 3—delivering a 30% overall rise broken down into a 20% general increase plus a 10% ringfenced portion dedicated specifically to disrupting the illegal gambling market. Set to take effect on 1 October 2026, these changes come at a time when the sector faces additional headwinds from the Remote Gaming Duty jumping to 40% come April 2026, putting extra strain on licensed operators' margins.
What's interesting here is how the proposals tie directly into sustaining frontline enforcement activities, protecting revenue streams for legitimate businesses from black market rivals, and funding the rollout of reforms outlined in the government's post-White Paper agenda; fees, currently hovering at 0.21% of Gross Gambling Yield (GGY), could climb as high as 0.28% under the new model, reflecting a calculated shift toward risk-based and market-proportionate charging. The consultation document lays out these details transparently, inviting feedback from stakeholders until early summer, a process that observers note often shapes final policies in this tightly regulated space.
Breaking Down the Proposed Fee Structure
Option 3 stands out as the government's favored approach, blending a broad 20% uplift across all fee categories with that extra 10% earmarked for tackling illicit operators; remote gambling businesses, which dominate online betting and casino play, would see some of the steepest hikes since their activities draw heavier regulatory scrutiny due to cross-border risks and higher volumes. And while non-remote operators like land-based casinos and bingo halls face increases too, the focus sharpens on digital firms whose growth has exploded in recent years, fueled by mobile apps and live streaming integrations that keep punters engaged longer.
Turns out the formula isn't arbitrary; it factors in each operator's GGY—essentially their net revenue after payouts—alongside compliance history and the inherent risks of their offerings, so a high-roller poker site might pay more than a low-stakes slots provider even if GGYs match. Data from the Gambling Commission's Industry Statistics Annual Report (Financial Year April 2024 to March 2025) underscores why this matters, revealing remote sectors posting GGYs up significantly year-over-year, which in turn ramps up the Commission's workload for monitoring and interventions. Those who've tracked these trends know that as volumes swell—especially with major events like the Euros or Cheltenham on the horizon—the black market siphons off shares, estimated in billions, prompting calls for beefed-up defenses.
But here's the thing: the ringfenced 10% isn't just additive; it funds targeted ops against unlicensed sites, overseas raiders, and money laundering schemes that prey on UK players, ensuring licensed firms aren't undercut while regulators stay ahead of tech-savvy fraudsters using VPNs and crypto. Effective from October 2026, this timing aligns neatly with the tax duty spike in April, giving operators a runway to adjust but also piling on costs when revenues face compression.
Context Amid Industry Pressures and Growth
As of March 2026, with spring racing festivals underway and football seasons winding down, the gambling landscape buzzes with activity, yet licensed operators navigate a gauntlet of rising costs; the proposed fees arrive alongside that 40% Remote Gaming Duty, which hits online gross profits harder than before, squeezing what was already a competitive field where margins run thin. Figures indicate remote GGY has ballooned, driven by younger demographics embracing in-play betting on their phones, but so have enforcement demands—think thousands of interventions yearly against rogue operators advertising via influencers or pop-ups.
Experts who've studied the sector point out that without these hikes, the Commission risks underfunding, leading to slower responses against illegal markets that offer unchecked odds and no player protections; one case that highlights this involved a crackdown on overseas sites targeting UK punters during last year's Grand National, where unlicensed books lured bets with inflated payouts, only for players to lose winnings when push came to shove. The consultation emphasizes how Option 3 sustains these efforts, channeling funds into intelligence gathering, site blocks, and partnerships with payment providers to choke off illegal flows.
Now, smaller operators might feel the pinch most acutely since fees scale with GGY, but larger players with diversified portfolios—like those blending sportsbooks with casinos—could absorb it better, especially if black market deterrence boosts their share; that's where the rubber meets the road, as reforms from the 2023 White Paper roll out stricter affordability checks and stake limits, demanding even more oversight. People in the industry often discover that proactive compliance pays off, turning regulatory costs into shields against fines or license revocations that dwarf fee bumps.
Stakeholder Impacts and Broader Implications
Remote betting firms, cornerstones of the UK's £15 billion-plus gambling economy, stand to see application fees, annual charges, and compliance costs all rise under the plans, with the 0.21% to 0.28% GGY shift meaning a mid-tier operator on £100 million GGY pays an extra £70,000 yearly—multiplied across the board, that's millions redirected from profits to regulation. Yet this aligns with the principle that bigger risks, bigger contributions, so high-risk segments like casino products bear more weight while lotteries or society lotteries see lighter touches.
It's noteworthy that the consultation runs through spring 2026, overlapping with budget season and potential tweaks, giving trade bodies like the Betting and Gaming Council room to lobby; past feedback loops have softened edges, such as phased implementations or exemptions for startups, though sources suggest Option 3's momentum holds firm given fiscal realities. Observers note how this fits a pattern: post-pandemic growth spurred reforms, and now with March 2026 data showing sustained volumes, the government doubles down on sustainability.
Take one scenario where a remote operator expands into esports betting; under current fees, regulatory costs lag the added scrutiny, but the new model catches up, funding checks on age verification and problem gambling flags that protect players and firms alike. And while tax hikes loom, these fees aim to level the field against black marketeers who dodge duties entirely, preserving the 90%+ licensed market share that's a point of pride for UK regulation.
Conclusion
The public consultation on Gambling Commission fee increases marks a strategic pivot, pushing for a 30% uplift via Option 3 to fortify enforcement against illegal competition while mirroring industry growth and risks; effective October 2026 amid the Remote Gaming Duty escalation, it underscores a commitment to robust oversight in a booming yet challenged sector. Stakeholders weigh in now, shaping details that could define operator viability for years, with data confirming the need as GGYs climb and threats persist. Ultimately, those navigating this landscape find that aligned costs breed resilience, keeping licensed gambling front and center.