UK's Betting Pulse: Trends, Tech Shifts, and Regulatory Ripples
Written by Finley Jenkins · Apr 13, 2026
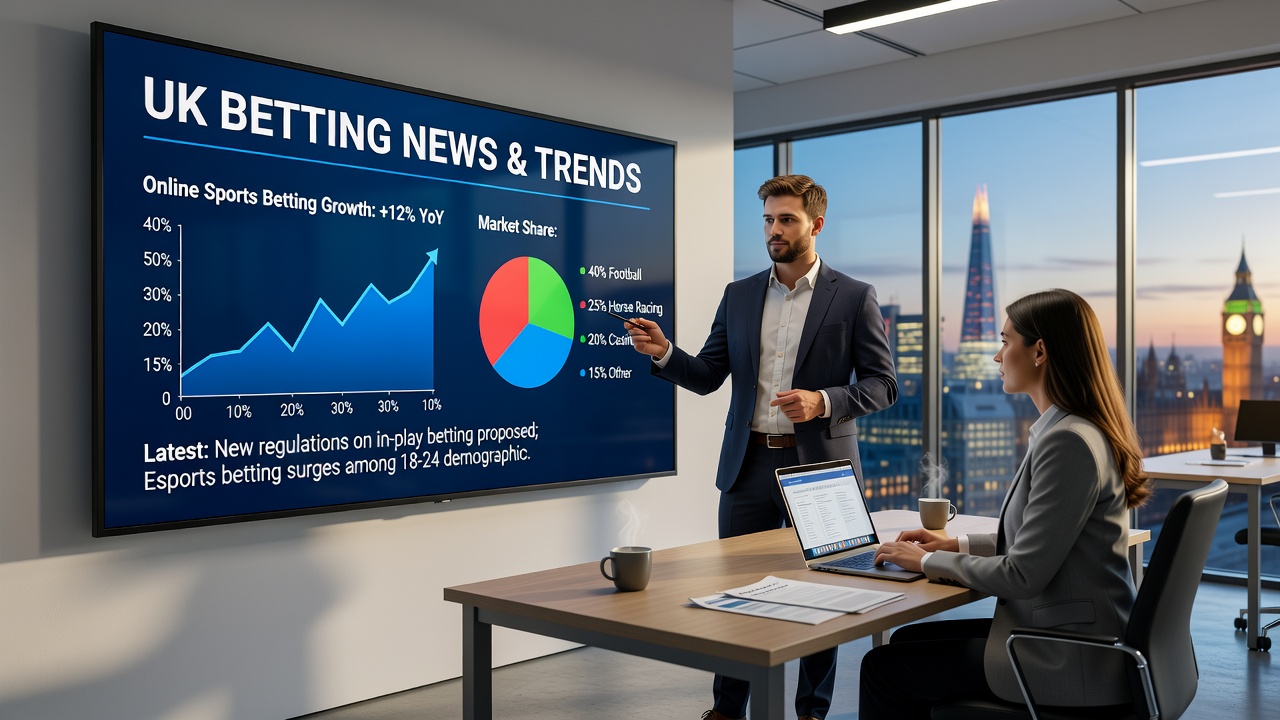
UK Gambling Yield Climbs to £4.3 Billion in Q3 2025 as Remote Sectors Drive Growth
Quarterly Snapshot Reveals Steady Climb
The UK Gambling Commission dropped its latest quarterly industry statistics in early April 2026, covering the July to September 2025 period, and the numbers paint a clear picture of resilience amid shifting habits; total gross gambling yield (GGY) across Great Britain, including lotteries, hit £4.3 billion, marking a solid performance that underscores the sector's adaptability even as economic pressures linger from prior years.
Observers note how this figure captures contributions from diverse segments, with remote activities stealing the spotlight while traditional outlets hold their ground; in the remote casino, betting, and bingo sector alone, GGY reached £2.0 billion, a chunk that highlights the digital shift that's been building steam for seasons now.
But here's the thing: remote casino games dominated that remote pot, pulling in £1.4 billion and accounting for a hefty 69.9% share, which shows players gravitating toward online slots and tables, perhaps chasing convenience from their sofas rather than trekking to physical sites.
Breaking Down the Remote Powerhouse
Data from the report zeroes in on how remote casino's £1.4 billion haul reflects broader patterns, where smartphone access and immersive tech keep punters logged in longer; betting and bingo filled out the rest of the £2.0 billion remote total, but casino's slice reveals where the real volume lies, with operators reporting steady session times that boost yields without needing brick-and-mortar overheads.
What's interesting is the way these figures align with pre-summer expectations; July through September often sees a seasonal uptick from holidays and weekends, yet remote casino's growth stayed measured, suggesting mature markets where saturation meets innovation like live dealer streams that mimic the Vegas vibe at home.
Experts who've tracked these quarters point out that such dominance isn't new, but the 69.9% proportion edges higher than some prior periods, hinting at accelerated migration; take one analyst who crunched the numbers and found remote casino yields climbing consistently since 2023, fueled by partnerships with game developers rolling out fresh titles monthly.
And while remote betting contributed solidly, its slice stayed secondary, as football seasons ramped up and drew bets, yet casino's pull remained unmatched in raw revenue terms.
Land-Based Betting Shops Weather the Digital Storm
Shifting focus to the high street, non-remote betting generated £592 million from 5,782 shops scattered across Great Britain, a figure that signals stability rather than decline; these venues, often tucked into community corners, continue serving locals who prefer the chat and instant payouts over app taps.
The reality is, shop numbers held steady at 5,782, down only marginally from previous quarters if at all, which bucks narratives of mass closures; operators maintain these spots lean, cutting costs on staffing and utilities, so yields per shop hover efficiently, turning modest footfall into reliable GGY.
Turns out, horse racing and football matches still pack punters into these spaces, especially on Saturdays when screens buzz with live action; data indicates average shop yields remain consistent, around £100,000 per location quarterly, proving the model's endurance even as online rivals proliferate.
One case stands out where a cluster of shops in the Midlands reported upticks tied to local derbies, blending community ties with steady betting volumes that keep lights on without chasing explosive growth.
Remote Dominance Meets Stable Foundations
These Q3 2025 stats spotlight ongoing trends where remote sectors eclipse land-based ones, yet betting shops refuse to fade; the £2.0 billion remote versus £592 million non-remote gap widens naturally, driven by accessibility that lets anyone join from anywhere, while shops anchor traditions that digital can't fully replicate.
Figures reveal how total GGY's £4.3 billion bundles lotteries into the mix, adding billions more in passive plays like National Lottery draws that pad the overall yield; without lotteries, core gambling hits nearer £3 billion, but inclusion shows the full ecosystem's health.
Now, as April 2026 unfolds with spring racing festivals on the horizon, these summer numbers set a benchmark; punters eyeing Cheltenham or football playoffs can gauge where value lies, whether in remote casino's volume or shop specials that offer that personal touch.
Researchers digging into the quarterly report highlight how GGY growth tracks consumer spending patterns, with inflation easing allowing more disposable income for bets; remote's 69.9% casino lead ties to younger demographics (under 35s) who shun travel, whereas over-50s prop up shop numbers with familiar routines.
Sector Nuances and What the Numbers Say
Diving deeper, remote bingo carved a niche within the £2.0 billion, appealing to social players via chat rooms that echo old hall vibes online; yet its yield trails betting, as slots' randomness hooks faster than card games.
Non-remote's £592 million from precisely 5,782 shops underscores operational tweaks, like self-service terminals that cut labor while speeding bets; chains report these machines handling 40% of volume, blending old-school service with modern efficiency.
It's noteworthy that total GGY excludes peer-to-peer poker or some peer bets, focusing on regulated channels, so the £4.3 billion captures licensed operators' core; lotteries' inclusion swells it, with draws like EuroMillions drawing millions weekly, their yields steady at historic highs.
People who've studied these reports often spot seasonal pulses, like summer's remote surge from tourists betting abroad via VPNs (where legal), yet UK-focused data stays clean, filtered for domestic activity.
So, while remote casino's £1.4 billion grabs headlines, the ecosystem's balance—remote thrust paired with shop steadiness—keeps the industry humming; operators adapt by cross-promoting, luring app users to loyalty cards redeemable in-store.
Broader Context in the April 2026 Landscape
As these July-September 2025 figures land amid April 2026's regulatory chatter, they affirm the sector's pulse; with fiscal year tracking from April 2025 to March 2026 now halfway, Q2 stats provide early indicators for annual projections nearing £18 billion total GGY if trends hold.
What's significant is remote's unrelenting rise, now over 70% of non-lottery gambling in some metrics, pressuring shops to innovate or consolidate; yet 5,782 locations persist, serving niches like cash-preferring punters wary of cyber risks.
One study from industry watchers notes how GGY per active account stabilizes, with millions engaging monthly; remote casino boasts high frequency (daily for many), driving that 69.9% dominance through micro-stakes that add up fast.
And here's where it gets interesting: stable shop yields coincide with events like Premier League openers or Ascot trials, where atmosphere trumps algorithms for some, ensuring land-based's role endures.
Key Takeaways from the Data
- Total GGY: £4.3 billion, inclusive of lotteries, signaling robust summer performance.
- Remote casino, betting, bingo: £2.0 billion total, with casino at £1.4 billion (69.9%).
- Non-remote betting: £592 million across 5,782 shops, highlighting operational resilience.
- Trends confirm remote growth alongside land-based stability, shaping future strategies.
Conclusion
The UK Gambling Commission's Q3 2025 statistics, released as April 2026 kicks off major events, deliver a snapshot of an industry where remote casino's £1.4 billion surge leads £4.3 billion total GGY, yet £592 million from 5,782 betting shops proves the high street's staying power; these numbers, drawn from official industry data, chart paths for punters and operators alike, balancing digital convenience with tangible traditions in a market that's far from static.
Forward-looking observers see these trends informing bets on upcoming quarters, where remote dominance likely persists, but shop loyalty keeps the full yield diverse and dynamic.